Lenders That Will Lend You More: 55 UK Lenders Above 4.5x Income (November 2026)
The short answer
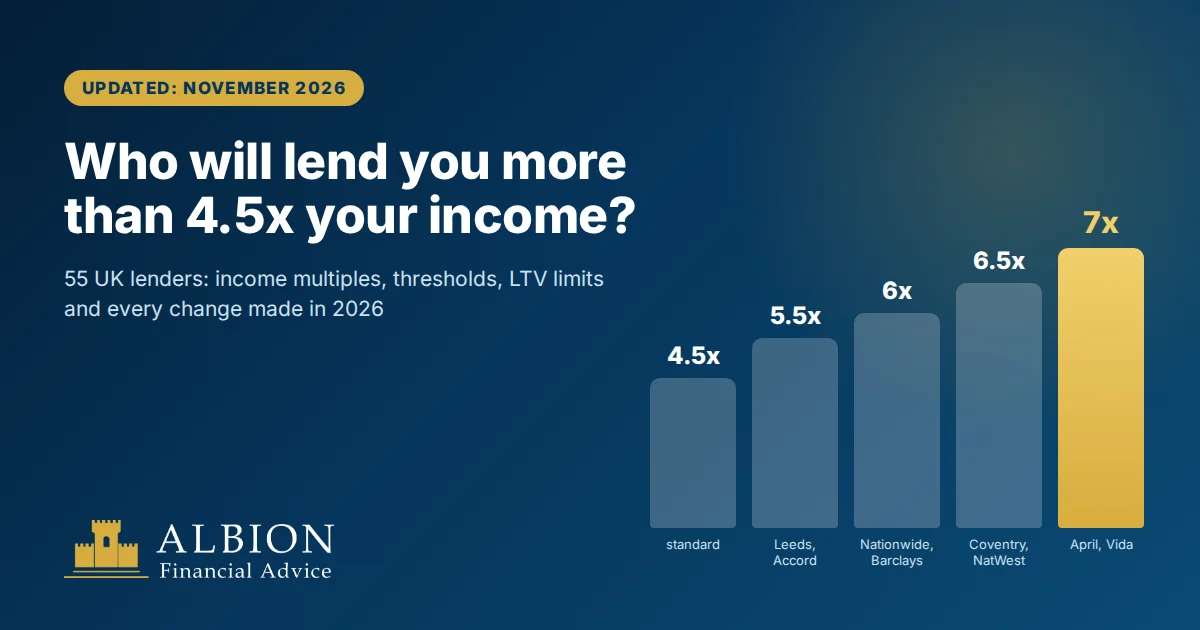
- 7x income is today's maximum: April Mortgages, Vida Homeloans and Teachers Building Society (for education staff). 6.5x: HSBC Premier, NatWest, Nationwide, Coventry, Nottingham, Tipton and West One. Hodge, West One LTI Boost, Market Harborough and The Stafford have no multiple cap at all.
- Lowest thresholds: Coventry gives first-time buyers 6.5x from £30,000, Nationwide 6x from £30,000, and Accord 5.5x with no income threshold at all.
- Since 28 October 2026 the 15% limit on loans at 4.5x or more applies to the market as a whole, not to each lender, so lenders have more room.
- A higher multiple always depends on affordability, your deposit, credit history and how you are employed.
The usual ceiling on mortgage borrowing in the UK is 4.5 times gross annual income (4.49x at many lenders). In 2026 it stopped being the rule. The Bank of England allowed lenders to write more high-multiple loans, and banks and building societies were quick to use the room: Mortgage Broker Tools data from July 2026 showed four times as many lenders offering 6x as a year earlier.
This guide brings together 55 lenders that lend above 4.5x income, plus the private banks that use no fixed multiple. We checked their criteria on 10 November 2026 directly on each lender's intermediary website and in its criteria documents. Each profile lists every tier (multiple, income, maximum LTV and who qualifies), the key conditions and a link to the source. Changes from recent months are flagged with coloured labels.
Not sure which lender would lend you the most? We can check your borrowing across all of them at once, with no effect on your credit file.
What changed in 2026
2026 has seen the fastest loosening of income multiples in the UK for a decade. Below is every change we confirmed with the lenders and regulators, newest first. Changes after June 2026 carry a "since June" label. The only tightening is Accord's income threshold, and the only lender to leave the market is Clydesdale Bank.
| Date | Lender | What changed | Verdict |
|---|---|---|---|
| 28 October 2026 | PRA / FCA | The Bank of England (PRA) and the FCA remove the 15% cap on lending at 4.5x or more for individual lenders. Only the market-wide limit remains. since June | Regulation |
| 22 October 2026 | Furness Building Society | 6x from £80,001 to 90% LTV (new tier). since June | Higher multiple |
| 5 October 2026 | Skipton Building Society | 6x to 90% LTV (was 5.5x) and 5.5x at 95% (was 5x). since June | Higher multiple |
| 29 September 2026 | West One Loans | No-cap LTI Boost available to 85% LTV (was 80%). since June | Better terms |
| 9 September 2026 | Scottish Building Society | Enters England and Wales: 5x for professionals to 95% LTV. since June | New to this list |
| 2 September 2026 | Atom bank | Higher multiples at 90% LTV for £45,000 to £60,000; 6x from £75,000. since June | Higher multiple |
| 1 September 2026 | Coventry Building Society | 6.5x for first-time buyers to 95% LTV, from £30,000 sole / £50,000 joint. since June | New to this list |
| 21 August 2026 | Foundation | 5.99x from £50,000 sole / £70,000 multiple applicants, and for professionals. since June | New to this list |
| 19 August 2026 | HSBC UK | Higher maximum loan sizes (£775,000 at 90% LTV). since June | Better terms |
| 6 August 2026 | West One Loans | Prime tier: up to 6.5x at 90% LTV for minor adverse credit. since June | Higher multiple |
| 16 July 2026 | Nationwide Building Society | 6x for movers from £75,000 now includes the self-employed; existing borrowers have no minimum income. since June | Higher multiple |
| 16 July 2026 | Leeds Building Society | Start Mortgage: 98% LTV, up to 5x income from £30,000. since June | New to this list |
| 1 July 2026 | Clydesdale Bank | No more new mortgages (business moved to Nationwide). since June | Withdrawn |
| 30 June 2026 | Hodge | No multiple cap for incomes of £40,000+, to 95% LTV. since June | Higher multiple |
| 3 June 2026 | Tipton & Coseley Building Society | 6.5x range relaunched (to 80% LTV). | New to this list |
| 26 May 2026 | West Brom Building Society | 5x from £40,000 (was £50,000), 5.75x from £60,000 (was £75,000). | Higher multiple |
| 20 May 2026 | Accord Mortgages (Yorkshire Building Society) | Threshold above 4.49x for non-first-time buyers: £65,000 (was £50,000). | Tightened |
| 20 May 2026 | West One Loans | Core range 5.5x (was 5x). | Higher multiple |
| 19 May 2026 | NatWest | 6.5x for couples on £150,000+ to 75% LTV. | Higher multiple |
| 14 April 2026 | Leeds Building Society | Income Plus: 6x from £75,000 (was a 5.5x maximum), now for movers and remortgage too. | Higher multiple |
| 10 April 2026 | Principality Building Society | 5.5x for first-time buyers from £30,000 (was £40,000). | Higher multiple |
| 8 April 2026 | TSB | 5x and 5.5x for the self-employed too. | Higher multiple |
| 10 March 2026 | Newbury Building Society | 5x with £30,000+ income after commitments. | New to this list |
| 26 February 2026 | Bank of Ireland UK | Standard range up to 5x (from £40,000 / £50,000). | New to this list |
| 6 February 2026 | Leek Building Society | 6x to 95% LTV on referral. | Higher multiple |
| 28 January 2026 | NatWest | NatWest's first 6x tier. | Higher multiple |
| 21 January 2026 | Nationwide Building Society | 6x for movers and remortgage with extra borrowing, to 95% LTV. | Higher multiple |
| 13 January 2026 | Metro Bank | 6x for professionals, 5x from £70,000. | New to this list |
| 12 January 2026 | Bank of Ireland UK | Bespoke range up to 6x. | New to this list |
The new rules: no more 15% cap per lender
Since 2014 the Bank of England's Financial Policy Committee (FPC) limited loans at 4.5 times income or more to 15% of each lender's new mortgages. That is why 4.5x became the default ceiling and lenders kept higher multiples for selected customers.
- July 2025: the FPC recommended applying the 15% limit to the market as a whole, letting individual lenders go above it. The PRA brought in interim waivers, and the threshold below which a small lender is exempt altogether rose to £150m of lending or 300 mortgages a year.
- 14 October 2026: the PRA (PS19/26) and the FCA (FG26/11) published the final rules. From 28 October 2026 there is no 15% cap for individual lenders. Each decides its own approach, as long as the market as a whole stays within 15%.
- The safety valve: if the market-wide share of loans at 4.5x or more goes over 15%, lenders above that level will have to scale back gradually each quarter. The FCA says lenders "should not operate on the basis that they can permanently maintain" a share above 15%.
- Where the market is: in Q2 2026 loans at 4.5x or more made up 14.1% of new lending (9.7% a year earlier), and 18.1% among first-time buyers. FCA data published in November 2026 show first-time buyer loans at 5.5x or more up 142% in a year, to 7,621.
- What next: on 31 October 2026 the Financial Times reported that the FPC is considering raising the "high LTI" threshold from 4.5x to 5x, as UK Finance has asked. Nothing has been decided; the next FPC meeting is on 19 November 2026.
Remember the other side: on 5 November 2026 the Bank of England raised Bank Rate to 4%, and two-year mortgage rates had risen by almost half a percentage point since September. Higher rates mean a tougher stress test, so the figure you are offered can be lower than the multiple alone suggests.
Which lender fits your situation
The highest multiple on paper is not always open to you. Start from your own situation, and click a name to jump to the full profile.
First-time buyer on £30,000+
Coventry Building Society: 6.5x from £30,000 sole, to 95% LTV, not self-employed. Nationwide Building Society Helping Hand: 6x from £30,000. Leeds Building Society, Principality Building Society and Hanley Economic Building Society: 5.5x from £30,000. Accord Mortgages (Yorkshire Building Society): 5.5x with no income threshold at all.
Household income of £75,000+
6x: Leeds Building Society, Nationwide Building Society, Barclays (to 85% LTV), Atom bank, Newcastle Building Society, NatWest (joint). 6.5x with no threshold: Nottingham Building Society Make it Possible. 7x: April Mortgages (from £50,000 on a 10+ year fix), Vida Homeloans (from £60,000).
Regulated profession (doctor, solicitor, accountant...)
6x: Metro Bank (no minimum income, 90% LTV), Kensington Mortgages (from £35,000), Saffron Building Society, Chorley Building Society. 5.99x: Foundation. No cap: Vernon Building Society (to 85% LTV). 5.5x: Principality Building Society, Swansea Building Society (doctors, dentists).
Teacher, NHS or emergency services (key worker)
7x for education staff: Teachers Building Society (to 95% LTV). 5.49x: Foundation. 5x: Kensington Mortgages Hero. No deposit: Gable Mortgages 5.5x for key-worker couples at 100% LTV.
Self-employed or company director
6x: Nationwide Building Society High Income (from £75,000), April Mortgages (2 years' trading). 5.5x: TSB, Atom bank, Newcastle Building Society. 6.5x: West One Loans Extra (from 1 year). Note: Coventry Building Society, Helping Hand, Virgin Money and Principality Building Society do not give the self-employed an enhanced multiple.
Small deposit (5% or less)
95% LTV: Coventry Building Society 6.5x, Nationwide Building Society 6x, Teachers Building Society 7x, Perenna 6x, Precise Mortgages (OSB Group) 6x, Hodge no cap, Skipton Building Society 5.5x. 97.5%: West One Loans 6.5x. 98%: Leeds Building Society Start 5x, Cambridge Building Society 5.5x. 100%: Hanley Economic Building Society Rent to Own 5x, Family Building Society 5.33x.
Like-for-like remortgage
Nationwide Building Society: 6.5x. Santander, TSB, Virgin Money, Halifax / Lloyds Bank: 5.5x. No cap: Hanley Economic Building Society and Foundation (pound for pound). Useful if you are a "mortgage prisoner" with your current lender.
No fixed multiple at all
Hodge (from £40,000, to 95%), West One Loans LTI Boost (from £50,000, to 85%), Market Harborough Building Society, The Stafford Building Society, Saffron Building Society Premier Income (from £150,000). What counts is the budget: income minus spending and commitments.
Every lender in one table
Lenders sorted from the highest multiple down. The columns show the conditions for each lender's top multiple; lower tiers are in the profiles. On a phone, scroll the table sideways.
| Lender | Max multiple | Income condition at the maximum | Max LTV at the maximum |
|---|---|---|---|
 Hodge Higher multiple | no cap | from £40,000 (sole or joint) | 95% |
 Market Harborough Building Society New to this list | no cap | subject to affordability | 80% |
 Melton Building Society | case by case | Melton affordability calculator | 100% |
 Saffron Building Society | no cap | from £150,000 | 80% (70% interest-only) |
 The Stafford Building Society New to this list | no cap | subject to affordability | 95% |
 Vernon Building Society New to this list | no cap | professionals (including doctors, nurses, teachers, solicitors, accountants, engineers, pilots) | 85% |
 West One Loans Higher multiple | no cap | household income from £50,000 | 85% |
| Arbuthnot Latham, C. Hoare & Co, Handelsbanken, Lloyds Private Banking | case by case | Arbuthnot Latham: loans from £500,000, £750,000 relationship | 60% |
 Coutts | case by case | new clients: loans above £1.5m; no minimum income | 90% |
 Investec | case by case | £300,000+ a year and £3m+ net worth | 95% in some cases |
 April Mortgages | 7x | £50,000+ (sole or joint) on a 10+ year fix | 85% |
 Teachers Building Society New to this list | 7x | education professionals; one applicant earning at least £13,000 | 95% |
 Vida Homeloans | 7x | from £60,000 a year | 90% |
 Coventry Building Society New to this list | 6.5x | from £30,000 sole / £50,000 joint | 95% |
 HSBC UK Better terms | 6.5x | HSBC Premier account | 90% |
 NatWest Higher multiple | 6.5x | joint income from £150,000 | 75% |
 Nationwide Building Society Higher multiple | 6.5x | no income threshold | per product |
 Nottingham Building Society | 6.5x | no minimum income | 90% |
 Tipton & Coseley Building Society New to this list | 6.5x | no published income threshold | 80% |
 Aldermore New to this list | 6x | from £60,000 | under 80% |
 Atom bank Higher multiple | 6x | employed, £75,000+ | 90% |
 Bank of Ireland UK New to this list | 6x | from £50,000 sole / £75,000 joint (one applicant at least £40,000) | 90% |
 Barclays Better terms | 6x | two highest earners combined £75,000+ | 85% |
 Bath Building Society New to this list | 6x | from £50,000 sole / £100,000 joint | per product |
 Chorley Building Society | 6x | professional's income (other applicants: standard multiple) | 90% |
 Cumberland Building Society New to this list | 6x | any income (sole or joint) | 80% |
 Furness Building Society Higher multiple | 6x | from £80,001 | 90% |
 Gatehouse Bank (Home Purchase Plan) New to this list | 6x | from £75,000 (sole or joint) | 80% FTV |
 Hanley Economic Building Society | 6x | from £75,000 (sole or joint) | 90% |
 Harpenden Building Society New to this list | 6x | no published threshold | 85% (75% interest-only) |
 Kensington Mortgages | 6x | from £35,000 sole / £50,000 joint | 90% |
 Leeds Building Society Better terms | 6x | household income over £75,000 | 95% first-time buyers, 90% movers and remortgage |
 Leek Building Society | 6x | main or joint income, on referral | 95% |
 Metro Bank New to this list | 6x | regulated profession, qualified in the last 10 years; no minimum income | 90% |
 Newcastle Building Society New to this list | 6x | from £75,000 (employed) | 90% |
 Perenna New to this list | 6x | no minimum income | 95% |
 Precise Mortgages (OSB Group) | 6x | minimum £10,000 (main applicant) | 95% |
 Skipton Building Society Higher multiple | 6x | from £40,000 sole / £60,000 joint | 90% |
 United Trust Bank | 6x | minimum £15,000 (to 85% LTV) | 85% |
 Foundation New to this list | 5.99x | sole £50,000+, multiple applicants £70,000+; or professionals | 90% |
 West Brom Building Society New to this list | 5.75x | over £60,000 | 90% |
 Accord Mortgages (Yorkshire Building Society) Tightened | 5.5x | no minimum income | 95% |
 Beverley Building Society New to this list | 5.5x | as standard | per product |
 Cambridge Building Society New to this list | 5.5x | household income (sole or joint) | 98% |
| Gable Mortgages | 5.5x | key workers, joint application; minimum £25,000 | 100% |
 Gen H (Generation Home) New to this list | 5.5x | combined gross income from £50,000 | 95% |
 Halifax / Lloyds Bank | 5.5x | total household income over £40,000 | 90% |
 Hinckley & Rugby Building Society New to this list | 5.5x | qualifying standard income | 95% |
 Marsden Building Society New to this list | 5.5x | from £75,000 sole / £100,000 joint | per product |
 Principality Building Society | 5.5x | from £30,000 | 95% (first-time buyers) |
 Santander | 5.5x | from £100,000 (combined) | 90% |
 Swansea Building Society New to this list | 5.5x | from £30,000; at least one registered doctor or dentist | 80% |
 TSB New to this list | 5.5x | from £75,001 | 85% |
 The Mortgage Lender / Bluestone (Shawbrook) New to this list | 5.5x | from £50,000 sole / £70,000 joint | 90% |
 Virgin Money | 5.5x | from £75,000 | 85% |
 Suffolk Building Society New to this list | 5.49x | one applicant over £75,000, or 12 months of rent within 10% of the new payment | per product |
 Family Building Society New to this list | 5.33x | Family Mortgage | 100% |
 Newbury Building Society New to this list | 5x | £30,000+ after commitments | per product |
 Scottish Building Society New to this list | 5x | professionals (accountants, dentists, doctors, solicitors, actuaries, optometrists; pharmacists and vets who are partners or owners) | 95% |
Already have a lender in mind? Before you apply, let us check that you meet its conditions. Every declined application leaves a mark on your credit file.
Banks and the biggest lenders
Contrary to what many people assume, the big banks were among the quickest to raise their multiples after the rules changed. Several now lend 6x and two go to 6.5x, usually with higher income thresholds and a bigger deposit. Clydesdale Bank, which we covered in June, stopped taking new mortgage business on 1 July 2026.
Nationwide Building SocietyUK's largest building society
6.5xThe UK's largest mutual now lends up to 6x income to first-time buyers, home movers and existing customers, and up to 6.5x on a like-for-like remortgage.
- First-time buyer = no mortgage in the last 3 years; Helping Hand is for the original purchase only (not Right to Buy, Help to Buy or First Homes).
- For movers and remortgage on 5 to 10-year fixes Nationwide also has an "Extra help with affordability" route from £40,000 sole / £70,000 joint, self-employed included.
- Everything else: 4.49x; equity share 4.49x; further advances 4.75x.
Sources: Nationwide for Intermediaries - Affordability; Nationwide for Intermediaries - Borrower types (Helping Hand); Nationwide for Intermediaries - Helping Hand (checked 10 November 2026).
HSBC UKbank
6.5xHSBC lends 6.5x income, but only to Premier account holders. For everyone else the ceiling is 5.5x, and first-time buyers reach it from £35,000.
- Multiples use total evidenced income: 100% of basic pay, variable pay, self-employed, rental and pension income.
- Over 90% LTV: 4.49x for everyone.
- first direct (HSBC group, direct only, not through brokers): up to 5.5x for first homes and 4.75x for everyone else; up to 95% LTV on purchases and 90% on remortgages.
Sources: HSBC UK for Intermediaries - All about HSBC UK (Aug 2026); HSBC Premier eligibility; HSBC UK for Intermediaries - Criteria: loan to income; first direct - Mortgages (checked 10 November 2026).
NatWestbank
6.5xNatWest changed its multiples four times in 2026. It now has one of the most detailed grids on the market: the higher the income and the deposit, the higher the multiple, with separate rules for sole and joint applicants.
- Enhanced multiples no longer need a higher credit score.
- The grid covers capital and interest, interest-only and part-and-part; residential new business only.
- Under £40,000: 4.45x to 90% LTV and 4.0x at 95% LTV.
Sources: NatWest Intermediary Solutions - Affordability; Mortgage Solutions, 19.05.2026 - NatWest 6.5x (checked 10 November 2026).
Barclaysbank
6xBarclays keeps it simple: 6x for households earning £75,000+ with at least a 15% deposit, open to everyone, not just premier customers.
- Threshold income = basic pay, sustainable allowances and self-employed income.
- If other debt repayments are 20% of income or more: max 4.0x. Over 90% LTV with income up to £50,000: 4.0x. Everyone else: 4.49x.
- Family Springboard: 4.0x (4.49x with income over £50,000). Mortgage Boost (JBSP) does not raise the multiple.
Source: Barclays for Intermediaries - Residential lending criteria (income multiples) (checked 10 November 2026).
Halifax / Lloyds Bankbank (Lloyds Banking Group)
5.5xHalifax and Lloyds Bank use a tiered grid: 5.5x for first-time buyers from £40,000 and for higher earners moving home.
- Like-for-like remortgage: up to 5.5x where the standard multiple would be lower (to 75% LTV).
- Over 90% LTV and the £5,000 deposit mortgage (since May 2026): 4.49x.
- Lloyds Bank offers the same First Time Buyer Boost (5.5x, 90% LTV).
Sources: Halifax Intermediaries - Criteria (Affordability, LTI and income multiples); Lloyds Bank - First-time buyer mortgages; Lloyds Bank - First Time Buyer Boost (checked 10 November 2026).
Santanderbank
5.5xSantander has one of the simplest grids: 5.5x from £100,000 of income, right up to 90% LTV.
- Under £45,000 and over 90% LTV: 4.45x.
- My First Mortgage (98% LTV for first-time buyers): max 4.45x.
- Self-employed: max 90% LTV. Santander says its multiples are guidance only and may change at short notice.
Source: Santander for Intermediaries - Residential lending criteria (November 2026) (checked 10 November 2026).
Virgin Moneybank (Nationwide group)
5.5xVirgin Money's business moved into Nationwide on 2 April 2026, but it keeps its own broker range and criteria.
- Max 4.49x if LTV is over 85%, if any applicant is self-employed (contractors excepted) or for shared ownership.
- Variable pay counted at 60%; rental income excluded.
Sources: Virgin Money for Intermediaries - Income multiples; Virgin Money - transfer to Nationwide (checked 10 November 2026).
TSBbank
5.5xTSB raised its multiples in April 2026 and, unusually, gives 5.5x to self-employed applicants too.
- Up to £50,000 and over 90% LTV: 4.49x.
- The maximum also depends on LTV and credit score. There is no separate 6x professional range.
Source: TSB Intermediary - Affordability criteria (checked 10 November 2026).
Metro Bankbank
6xSince January 2026 Metro Bank has lent 6x to young professionals and 5x to 5.5x to higher earners.
- Large Loan Range: 5.5x with no minimum income, to 85% LTV. Everyone else: 4.45x.
Sources: Metro Bank - Residential lending criteria (July 2026); Metro Bank for Intermediaries - Lending criteria (checked 10 November 2026).
Bank of Ireland UKbank
6xBank of Ireland raised the multiples on both of its ranges in 2026: up to 5x on standard and 6x on Bespoke.
- Joint applications under £50,000: 4.49x.
Source: Bank of Ireland for Intermediaries - Lending criteria (checked 10 November 2026).
Large and mid-sized building societies
Building societies are mutuals with no shareholders to satisfy. They have more freedom in how they lend, assess more cases by hand, and today they offer the highest multiples to first-time buyers, in some cases from £30,000 of income.
Leeds Building Societybuilding society
6xIn April 2026 Leeds raised the Income Plus maximum from 5.5x to 6x and opened the range to home movers and remortgages. It is one of very few lenders offering 5.5x from £30,000 of household income.
- Income Plus: minimum 5-year fix, capital and interest only, self-employed welcome, new-build flats to 85% LTV, 10% overpayments a year without charges, standard valuation included.
- First-time buyer = no mortgage in the last 3 years; one such applicant on a joint case is enough.
- Standard first-time buyer range: 5x; everyone else outside Income Plus: 4.49x.
Sources: Leeds BS for Intermediaries - Unlocking the next step; Leeds BS - We have expanded Income Plus (April 2026); Leeds BS - Mortgage lending criteria (effective 21.10.2026); Leeds BS - Start mortgages (July 2026) (checked 10 November 2026).
Coventry Building Societybuilding society
6.5xSince September 2026 Coventry has lent first-time buyers up to 6.5x income with a 5% deposit. It is one of the highest first-time buyer multiples at a large lender.
Source: Coventry for Intermediaries - First time buyer product guide (checked 10 November 2026).
Skipton Building Societybuilding society
6xIn October 2026 Skipton widened its LTI Booster: 6x up to 90% LTV and 5.5x with a 5% deposit.
- LTI Booster works on residential, Shared Ownership, First Homes, Help to Buy and LIFT products; not on Track Record, Delayed Start, product transfers or buy-to-let.
Sources: Skipton Intermediaries - LTI changes; Skipton Intermediaries - First-time buyers (checked 10 November 2026).
Accord Mortgages (Yorkshire Building Society)building society, broker-only brand
5.5xAccord is Yorkshire Building Society's broker-only brand. First-time buyers get 5.5x with no income threshold at all, even at 95% LTV.
- Up to 4.49x: everyone, to 95% LTV, no income threshold.
- Cascade-score cases: max 5x. £5k Deposit Mortgage: 4.49x.
- Yorkshire Building Society direct (Income Lifter, by phone only, not in Northern Ireland): up to 5.5x for first-time buyers or households earning over £65,000; 5x as standard.
Sources: Accord Mortgages - Criteria: loan limits; Accord Mortgages - Boost LTI; Yorkshire BS - Income Lifter (high LTI) mortgages (checked 10 November 2026).
Principality Building SocietyWales' largest building society
5.5xPrincipality gives 5.5x to first-time buyers and newly qualified professionals from £30,000 of income.
Sources: Principality for Intermediaries - Income boosts; Principality for Intermediaries - Income criteria (checked 10 November 2026).
Nottingham Building Societybuilding society
6.5xNottingham has a separate Make it Possible range: up to 6.5x income with no minimum income.
- Core range under £50,000: 4.49x.
Source: Nottingham BS for Intermediaries - Make it Possible (updated 26.10.2026) (checked 10 November 2026).
Newcastle Building Societybuilding society
6xNewcastle has an Enhanced+ range for higher incomes and larger loans, plus 5x on its standard range from £35,000.
- Over 90% LTV or income under £35,000: 4.49x.
Source: Newcastle BS - Residential lending policy (checked 10 November 2026).
Cumberland Building Societybuilding society
6xCumberland has some of the simplest rules: 6x with a 20% deposit whatever the income, and with a smaller deposit from £40,000.
- Under £40,000 with LTV over 80%: 4.49x. Gross income is used.
Source: Cumberland BS for Intermediaries - Residential lending criteria (checked 10 November 2026).
West Brom Building Societybuilding society
5.75xWest Brom lowered its income thresholds in May 2026: 5x from £40,000 and 5.75x from £60,000.
- Up to £40,000: 4.5x. Multiples above 4.5x are capped at 90% LTV. Based on the society's "allowable income".
Source: West Brom for Intermediaries - Lending and security guidelines (checked 10 November 2026).
Saffron Building Societybuilding society
no capSaffron has three routes: standard up to 5.5x, Professional Income Boost up to 6x, and Premier Income with no maximum multiple at all.
- Self-employed, contractors and JBSP on the standard range: 4.49x (5x at underwriter discretion to 80% LTV).
Sources: Saffron for Intermediaries - Lending criteria; Saffron BS - Professional Income Boost; Saffron BS - Premier Income (checked 10 November 2026).
Chorley Building Societybuilding society
6xChorley gives 6x only to newly qualified professionals, and applies it to the professional's own income.
- Standard: up to 4.49x total income (1 to 4 applicants).
- "Low start" option: interest only for the first 5 years. Houses to 95% LTV, flats to 90% (up to the 5th floor).
Source: Chorley BS for Intermediaries - Lending criteria (checked 10 November 2026).
Leek Building Societybuilding society (formerly Leek United)
6xSince February 2026 Leek can lend 6x income even at 95% LTV, but only on referral to an underwriter.
- Standard to 95% LTV: 4.49x. Shared ownership: 4.49x. Flats in buildings from 2020 onwards: up to 12 storeys.
Source: Leek BS for Intermediaries - Residential lending criteria A-Z (checked 10 November 2026).
Smaller building societies: often the most flexible of all
Little-known societies often have no fixed multiple at all and work from the household budget instead. In return they may cap loan sizes, lend only in certain areas or offer just a handful of products. This is the niche where a broker adds the most value.
Teachers Building Societybuilding society
7xTeachers Building Society lends education workers up to 7x income, even with a 5% deposit. Everyone else gets up to 5x.
- Purchase and remortgage to 95% LTV; remortgage with capital raising to 90%.
- Maximum loan: £2m to 75% LTV, £1.5m to 80%, £500,000 at 80-95%.
- Over 90% LTV: must be the only property owned, earned income and child benefit only, repaid before retirement and age 70.
Source: Teachers BS for Intermediaries - Lending criteria (checked 10 November 2026).
Tipton & Coseley Building Societybuilding society
6.5xTipton offers 5x on all its fixed and discount products, and up to 6.5x on its Higher Income Multiple range.
- Society minimum loan: £50,000.
Sources: Tipton for Intermediaries - Residential lending criteria; Tipton - Higher Income Multiple guide (23.07.2026) (checked 10 November 2026).
Market Harborough Building Societybuilding society
no capMarket Harborough has no maximum income multiple at all. Higher multiples sit in higher-priced product tiers.
- Criteria: "Loan to income (LTI): No maximum". No minimum income is stated.
Sources: Market Harborough BS - Criteria hub; Market Harborough BS - Intermediary product guide (30.10.2026) (checked 10 November 2026).
The Stafford Building Societybuilding society (Stafford Railway)
no capThe Stafford lends on an affordability model only, with no income multiple limit.
Source: The Stafford BS - Criteria guide (March 2026) (checked 10 November 2026).
Vernon Building Societybuilding society
no capVernon assesses professionals on guaranteed future income with no maximum multiple, and gives sole applicants up to 5.5x even at 95% LTV.
Source: Vernon BS - Mortgage product guide (from 1 June 2026) (checked 10 November 2026).
Hanley Economic Building Societybuilding society
6xHanley is not just its 100% LTV Rent to Own. On its other products it offers 5.5x from £30,000 and 6x from £75,000, and like-for-like remortgages have no multiple cap.
- Other products: 5x with no minimum income. Multiples are guidance; cases outside them can go to the Credit Committee.
- Fixed rates of 5 years or more are not stress-tested at a higher rate.
Sources: Hanley Economic BS - Credit risk & lending policy (Sept 2026); Hanley Economic BS - Lending criteria (checked 10 November 2026).
Furness Building Societybuilding society
6xIn October 2026 Furness added 6x for incomes over £80,000.
- Only basic income counts towards the multiple. Minimum income £20,000; up to £50,000: 4.5x. Self-build: 6x over £100,000.
Source: Furness BS for Intermediaries - Lending criteria (checked 10 November 2026).
Bath Building Societybuilding society
6xBath offers 5x to everyone and 6x from £50,000 sole or £100,000 joint.
Source: Bath BS for Intermediaries - Residential lending criteria (checked 10 November 2026).
Harpenden Building Societybuilding society
6xHarpenden lends up to 6x income.
Source: Harpenden BS - Residential criteria card (April 2026) (checked 10 November 2026).
Hinckley & Rugby Building Societybuilding society
5.5xHinckley & Rugby has an Income Flex range: 5.5x instead of the usual 4.49x.
- Up to two non-standard income sources, but those cases are capped at 4.49x.
Source: Hinckley & Rugby BS - Income Flex information sheet (March 2026) (checked 10 November 2026).
Marsden Building Societybuilding society
5.5xMarsden offers 5.5x from £75,000 sole or £100,000 joint.
- Below those thresholds: 4.5x.
Source: Marsden BS for Intermediaries - Residential criteria (checked 10 November 2026).
Beverley Building Societybuilding society
5.5xBeverley usually lends up to 5.5x and will consider more for trapped borrowers and in exceptional cases.
- Stress rate: 6.59%.
Source: Beverley BS - Lending criteria (checked 10 November 2026).
Suffolk Building Societybuilding society (formerly Ipswich)
5.49xSuffolk offers 5.49x if one applicant earns over £75,000, or if you can show 12 months of rent at a level close to the new mortgage payment.
- Standard 4.49x; no minimum income on standard applications.
Source: Suffolk for Intermediaries - Lending criteria (checked 10 November 2026).
Cambridge Building Societybuilding society
5.5xCambridge's First Step Mortgage combines 98% LTV with up to 5.5x household income.
Source: Cambridge for Intermediaries - First Step mortgage (checked 10 November 2026).
Swansea Building Societybuilding society
5.5xSwansea has a dedicated product for doctors and dentists at 5.5x income.
- The professionals and key worker (PROF26) and High Income (from £100,000 / £150,000) products do not state a multiple.
Source: Swansea BS - Medical professional mortgage (checked 10 November 2026).
Newbury Building Societybuilding society
5xSince March 2026 Newbury has offered 5x where income after commitments is at least £30,000.
- Below that: 4.75x. Shared ownership: 4.75x / 4.5x.
Source: Newbury BS - Updated affordability and income multiple criteria (checked 10 November 2026).
Family Building Societybuilding society
5.33xFamily Building Society can go up to 5.33x on its 100% Family Mortgage, where the family secures part of the loan.
- Standard mortgages: 4.5x, higher only by exception.
Source: Family BS for Intermediaries - Criteria A-Z (I) (checked 10 November 2026).
Scottish Building Societybuilding society
5xSince September 2026 Scottish Building Society has lent in England and Wales too. Professionals get 5x at 95% LTV.
- Standard: 4.5x sole and joint at every LTV.
Source: Scottish BS - Professional mortgages (checked 10 November 2026).
Melton Building Societybuilding society
case by caseMelton publishes no multiple: decisions rest entirely on the ability to repay. It offers a 100% LTV mortgage for first-time buyers.
Source: Melton BS for brokers - Lending criteria (checked 10 November 2026).
Specialist and challenger lenders
This is where you will find the highest multiples on the market (7x), no-cap lending for households earning £40,000 to £50,000 or more, and tolerance of minor credit blips. Most are broker-only, and rates can be a little higher than at the banks.
April Mortgagesspecialist lender (long-term fixes)
7xApril offers the highest multiple on the market, 7x, in return for a long fix of 10 or 15 years.
- Minimum income £24,000. Self-employed accepted (lower of the latest year or a 2-year average; 2 years' trading). Bonus, overtime and commission accepted. Up to 4 applicants. England and Wales only.
- Over 95% LTV (the 100% mortgage): below 4.5x. Like-for-like remortgage: as purchase up to 90% LTV.
- No CCJs or defaults in the last 36 months.
Source: April Mortgages - Key features (ORBPS0086) (checked 10 November 2026).
Vida Homeloansspecialist lender
7xVida lends up to 7x income from £60,000 of income and up to 90% LTV, with manual underwriting of complex incomes.
- Main applicant: minimum earned income £15,000. Maximum LTV 97% (to £750,000). Credit tiers Vida 36 / 24 / 6.
Sources: Vida Homeloans - Lending criteria; Vida Homeloans - Residential products (checked 10 November 2026).
Hodgespecialist bank
no capSince June 2026 Hodge has applied no income multiple cap at all for incomes of £40,000+, right up to 95% LTV.
- No minimum income. Applies to Resi, Resi Retire and RIO ranges.
Sources: Hodge for Intermediaries - Criteria; Hodge - Latest criteria changes (checked 10 November 2026).
West One Loansspecialist lender
no capWest One has three levels: 5.5x on the core range, 6.5x on the Extra plan to 97.5% LTV, and LTI Boost with no multiple cap at all.
- Permanent right to reside required. Since August 2026 a Prime tier offers up to 6.5x at 90% LTV for borrowers with minor adverse credit.
Sources: West One - Residential mortgages product guide (22.10.2026); Mortgage Solutions, 29.09.2026 - West One refreshes resi range (checked 10 November 2026).
Precise Mortgages (OSB Group)specialist lender
6xPrecise offers 6x with no profession restrictions, including borrowers with minor credit problems, up to 95% LTV.
- Outer limits: up to 5 defaults and 3 CCJs in the last 24 months; none in the last 3 months. Every case is credit-scored.
- Employed, self-employed, first-time buyers, movers and joint applicants.
Sources: Precise Mortgages - Residential; Precise Mortgages - Criteria (checked 10 November 2026).
United Trust Bankspecialist bank
6xUTB lends 6x across all its credit tiers up to 85% LTV and £2m.
- Debt-to-income up to 50%. Minimum income: £40,000 above 85% LTV, £25,000 for first-time buyers, £50,000 for interest-only.
- Contractors: day rate x 5 days x 48 weeks.
Source: United Trust Bank - Residential product guide (02.10.2026) (checked 10 November 2026).
Kensington Mortgagesspecialist lender
6xKensington has two "income stretch" ranges: 6x for professionals and 5x for public-sector heroes.
- Self-employed: 1 year's trading to 85% LTV, 2 years at 90-95%.
Source: Kensington - Income stretch: Professionals (checked 10 November 2026).
Aldermorespecialist bank
6xAldermore applies its multiple to total household income: 6x from £60,000 with a 20% deposit, and 5.5x from £80,000 even above 90% LTV.
- Under £40,000: 4.49x. Minimum income £10,000. 98% LTV for employed applicants only; self-employed and contractors to 95%.
Source: Aldermore - Residential criteria guide (July 2026) (checked 10 November 2026).
Atom bankdigital bank
6xAtom raised its multiples in September 2026: 6x from £75,000 to 90% LTV and 5.5x even at 95%.
- Under £45,000: 4.49x. Minimum income £16,000. Self-employed: 2 years' trading, max 90% LTV. The grid covers Prime and Near Prime.
Source: Atom bank for Intermediaries - Residential lending criteria (checked 10 November 2026).
Foundationspecialist lender
5.99xSince August 2026 Foundation has offered almost 6x (5.99x) to higher earners and professionals, with no cap on like-for-like remortgages.
- Everyone else: 4.49x.
Source: Foundation - Residential criteria guide (Aug 2026) (checked 10 November 2026).
Perennalong-term fixed-rate lender
6xPerenna specialises in 5 to 15-year fixes and lends up to 6x income even at 95% LTV.
Sources: Perenna for Intermediaries; Perenna - 5-year fixed added to range (checked 10 November 2026).
Gen H (Generation Home)digital lender
5.5xGen H lends 5.5x gross income from £50,000, including at 95% LTV.
- Under £50,000, or with an income booster (a family member's income): 4.49x.
Source: Gen H for Intermediaries - Criteria (checked 10 November 2026).
The Mortgage Lender / Bluestone (Shawbrook)specialist lenders
5.5xThe Mortgage Lender and Bluestone (Shawbrook group) raised their maximum from 4.5x to 5.5x in November 2025.
- Everyone else: up to 4.5x.
Sources: The Mortgage Lender - Residential products and criteria; Bluestone Mortgages - Residential product guide (checked 10 November 2026).
Gatehouse Bank (Home Purchase Plan)Islamic bank, Sharia-compliant finance
6xGatehouse offers a Sharia-compliant Home Purchase Plan, an alternative to an interest-bearing mortgage, at up to 6x income.
- FTV (finance to value) is the equivalent of LTV. Over 90% FTV: 4.49x (from £20,000). Under £35,000: 4.49x.
Sources: Gatehouse Bank - HPP criteria up to 80% FTV (20.10.2026); Gatehouse Bank - HPP criteria above 80% FTV (20.10.2026) (checked 10 November 2026).
Gable Mortgages100% LTV lender
5.5xGable lends with no deposit (100% LTV), and key workers get a higher multiple than everyone else.
- Everyone else: 4.49x, minimum income £27,780. Loans £125,000 to £1m, max 2 applicants, England and Wales only, no shared ownership.
Source: Gable Mortgages - Residential lending criteria (checked 22 October 2026).
Private banks and high-net-worth borrowers
Private banks do not publish income multiples. They look at the client's whole balance sheet and cash flow, and loans usually start at £500,000 to £1,500,000. Below is what they actually say in public.
Private banks can use lighter FCA rules for high net worth customers: people with net income of at least £300,000 a year or net assets of at least £3m. An affordability check still applies, just in a simpler form, and these loans are not excluded from the market-wide limit. Investec says it uses this route "very much the exception rather than the rule".
Couttsprivate bank (NatWest Group)
case by caseCoutts publishes no income multiple. It looks at the whole picture, including bonuses, carried interest and equity income.
Source: Coutts - Mortgage intermediaries (checked 10 November 2026).
Investecprivate bank
case by caseInvestec targets people earning £300,000+ a year with net worth of £3m+.
Source: Investec - Residential mortgages (lender page (2026 archived copy), checked 10 November 2026).
Arbuthnot Latham, C. Hoare & Co, Handelsbanken, Lloyds Private Bankingprivate banks
case by caseNone of these banks publishes a multiple. They look at the whole financial position, and entry levels are high.
Sources: Arbuthnot Latham - Borrowing; C. Hoare & Co - Mortgage brokers; Lloyds Bank Private Banking - Lending brochure (Feb 2026) (checked 10 November 2026).
How much more you could borrow: examples
Same income, different lenders. These are the maximums the multiples allow; the final figure depends on affordability, commitments and deposit.
Buying your first home alone on £35,000
£70,000 more than at 4.5x. Repayment at 5% over 30 years: £1,221 a month at the maximum, against £845 at 4.5x. Coventry and Helping Hand: employed applicants only.
A couple earning £60,000 between them
£150,000 more than at 4.5x. Repayment at 5% over 30 years: £2,255 a month at the maximum, against £1,449 at 4.5x. April 7x: up to 85% LTV on a 10 or 15-year fix.
A couple earning £90,000 between them
£225,000 more than at 4.5x. Repayment at 5% over 30 years: £3,382 a month at the maximum, against £2,174 at 4.5x. Nottingham Make it Possible: purchase only, up to 90% LTV.
Work out your own figure at different multiples with our affordability calculator.
10 criteria that decide the figure
The multiple is only the start. These rules are why two people on the same income can be offered very different amounts:
- Which income counts. Furness uses basic pay only, HSBC counts 100% of variable pay, Virgin Money 60%, Nottingham 75%. The same multiple can produce very different loans.
- Sole, joint or household threshold. Some lenders set separate thresholds (HSBC £35,000 / £55,000), others use combined income. "Over £40,000" (Lloyds) is not the same as "£40,000 or more".
- LTV, in other words your deposit. The bigger the deposit, the higher the multiple: NatWest and Aldermore set different multiples for each LTV band, and Barclays gives 6x only up to 85%.
- Length of the fix. April gives 7x only on a 10 to 15-year fix, Leeds Income Plus needs at least 5 years, Helping Hand 5 to 10 years. Fixes of 5 years or more often face a gentler stress test.
- Other debts (DTI). Leeds caps total secured debt (5.75x / 6.25x), Barclays drops to 4x when debt repayments reach 20% of income, UTB allows DTI up to 50%.
- Credit history and scoring. Bank of Ireland and Coventry require their scorecard to be passed, Halifax can cut the Boost to 5x, Chorley wants a spotless file. Precise tolerates minor blips.
- Employment type. The self-employed are excluded from, among others, Coventry's 6.5x, Helping Hand, Principality and Virgin Money's enhanced multiples.
- Profession and time since qualifying. Chorley: within 3 years, Principality: within 5 years, Metro and Saffron: within 10 years.
- Property type. New-build flats often get a lower LTV (Leeds, HSBC, Coventry: 85%), and some products exclude new build altogether.
- Who counts as a first-time buyer. Leeds and Nationwide: no mortgage in the last 3 years; Accord: never owned a property. On a joint case one such applicant is often enough.
What to watch with a high multiple
- A small deposit plus a high multiple raises the risk of negative equity if prices fall, which makes it harder to remortgage later.
- Long fixes (April 10 to 15 years, Perenna up to 15 years) give certainty, but carry early repayment charges. Check portability and overpayment allowances.
- The window could narrow. If the market goes above 15% of loans at 4.5x or more, lenders will have to rein them in. The share is already close (14.1%).
- Criteria change fast. NatWest changed its multiples four times this year. Always confirm the current rules before you apply.
How to go about it
- Work out your income the way lenders do: basic pay, bonus, overtime, self-employed income. Lenders count anything from 60% to 100% of variable pay.
- Get a rough figure with the affordability calculator at 4.5x, 5.5x and 6x.
- Match the lender to your profile: employment type, profession, deposit, credit history, property type.
- Get an agreement in principle (AIP/DIP) from the chosen lender, ideally through a broker who knows where the case will fit.
- Get your documents ready: last 3 payslips, P60, bank statements; self-employed: SA302s and Tax Year Overviews or company accounts.
Want to know what you could really borrow, and where? Get in touch and we will compare every lender on this list for you.
Sources
Each lender's criteria are linked in its profile. Market and regulatory sources:
- PRA PS19/26 - High loan to income lending (14.10.2026)
- FCA FG26/11 - High LTI lending guidance (October 2026)
- Bank of England - High loan-to-income lending data
- Bank of England - FPC record, September 2026
- Bank of England - Financial Stability Report, July 2026
- Bank of England - Monetary Policy Summary, November 2026
- FCA - Interest rate stress test rule
- FCA FS25/6 - Mortgage rule review feedback (December 2025)
- FCA Handbook - High net worth mortgage customer
- UK Finance - response on LTI in mortgage lending (July 2026)
- Mortgage Solutions - Number of lenders offering six times LTI quadruples (15.07.2026)
- Mortgage Solutions - High LTI lending more than doubles in 12 months (05.11.2026)
- Investing.com - Bank of England weighs raising high-risk mortgage threshold to five times income (31.10.2026)
Important: this article is for information only and is not financial advice or a product recommendation. Multiples, income thresholds and LTV limits come from lenders' published material as at 10 November 2026, may change without notice and do not guarantee that a mortgage will be offered. Every application is subject to affordability and the lender's criteria. We charge a broker fee, which we always confirm up front. Albion Financial Advice is authorised and regulated by the Financial Conduct Authority (FCA). Your home may be repossessed if you do not keep up repayments on your mortgage.
Dariusz Karpowicz
Director & Mortgage Adviser
Dariusz is a seasoned adviser with 15+ years in financial services. He founded Albion Financial Advice after gaining experience with established brokers, and has helped over 5,000 clients secure their ideal mortgage and protection solutions.
Frequently Asked Questions
Thinking about your next move? Message us on WhatsApp
Get personal, no-obligation mortgage advice from our FCA-regulated team. We reply fastest on WhatsApp.
We reply fastest on WhatsApp, message us anytime.